
Revenue Growth Masks Hidden Struggles
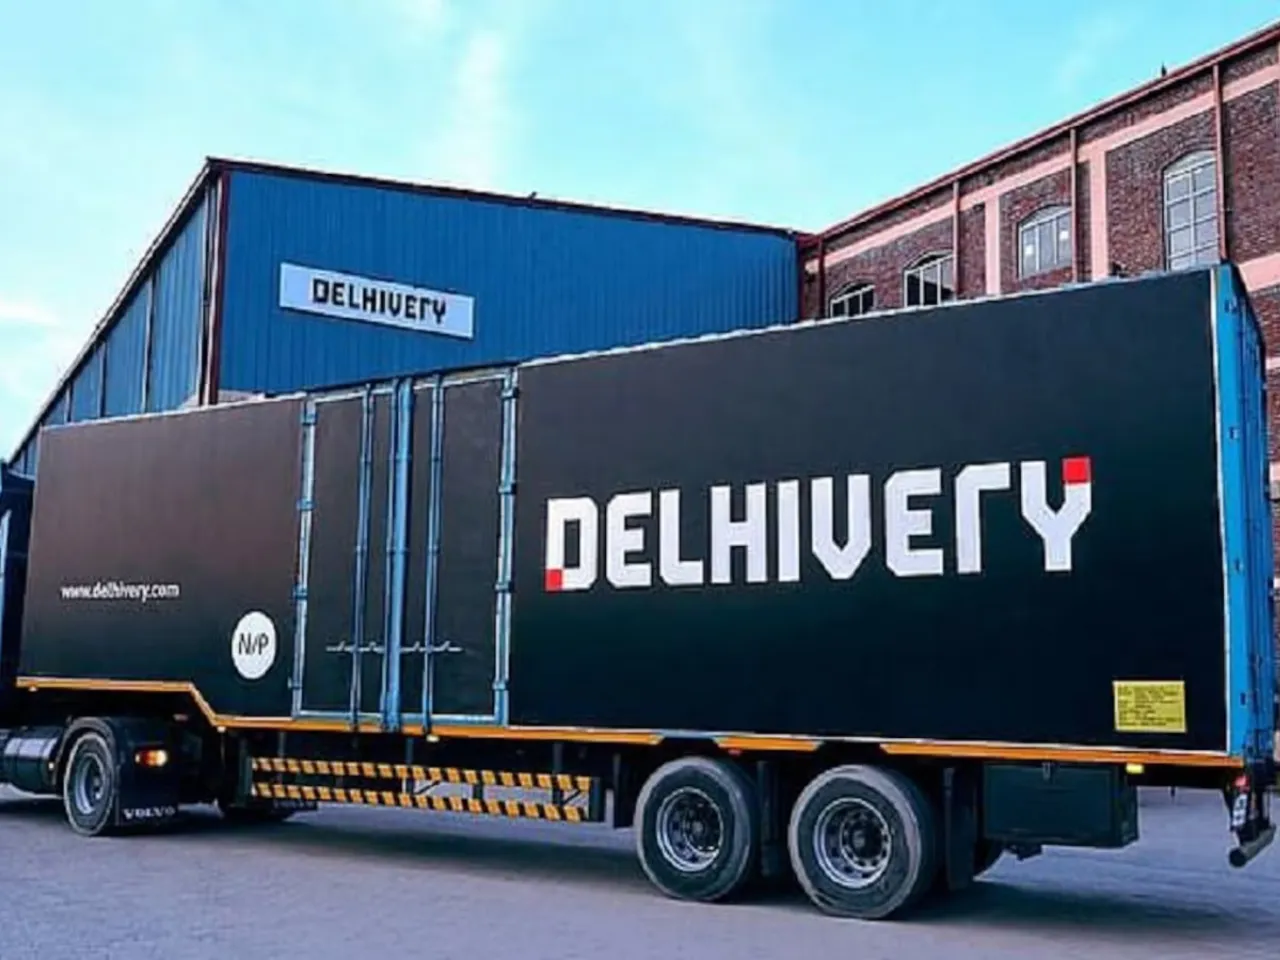
Uttamgram-based logistics leader Delhivery Ltd. stunned investors this week, reporting a 17% year-on-year revenue jump in Q2 FY26. The company’s topline grew to Rs 2,559 crore, up from Rs 2,190 crore in the same quarter last year—a clear sign of robust demand in India’s fast-evolving e-commerce logistics market.
But the good news comes with a twist. Delhivery slipped into a net loss of Rs 50 crore during the quarter, primarily due to one-time integration expenses from its recent Ecom Express acquisition. Without these costs, the company would have posted a net profit of Rs 59 crore—nearly six times the Rs 10 crore profit seen in Q2 FY25.
Strong Operational Performance Amid Challenges
Despite the headline loss, Delhivery’s operational metrics show significant improvement. EBITDA surged 162% YoY to Rs 150 crore, translating to a 5.9% margin. The growth underscores the company’s ability to scale efficiently and capture higher volumes even as it navigates complex mergers and acquisitions.
Revenue from services, excluding Ecom Express integration costs, came in at Rs 2,546 crore, up 16% year-on-year. This indicates that the core business is performing strongly, despite the temporary financial hit from merger-related expenditures.
Acquisition Costs Bite Hard
The Rs 90 crore spent on Ecom Express integration proved to be a heavy drag on profits. Total expenditure climbed 18% YoY to Rs 2,708 crore, outpacing revenue growth. Freight handling and servicing costs, which account for 68% of overall expenses, rose to Rs 1,843 crore, while employee benefits expenses climbed to Rs 426 crore.
Industry analysts note that while these one-time costs are a short-term pain, the integration is expected to yield long-term benefits, allowing Delhivery to expand its footprint and consolidate its position in India’s competitive logistics market.
A Strategic Move for Long-Term Growth
Delhivery’s Ecom Express acquisition is part of a broader strategy to strengthen its e-commerce delivery capabilities. By integrating Ecom Express, the company aims to enhance last-mile delivery networks, optimize freight operations, and drive synergies across technology platforms.
“Integration costs are a temporary hit, but the long-term strategic value is immense,” said an industry analyst. “Once the merger stabilizes, Delhivery could emerge as an even stronger force in India’s logistics sector.”
Investor Takeaways: Short-Term Loss, Long-Term Potential
While the Rs 50 crore loss may raise eyebrows, investors should focus on the operational growth and EBITDA performance, which suggest that Delhivery’s core business remains healthy. Revenue growth, margin expansion, and operational efficiency are all signs that the company is on track to leverage the Ecom Express acquisition for future profitability.
Moreover, the Indian logistics market continues to grow rapidly, fueled by e-commerce expansion, rising consumer demand, and increasing digital penetration. Delhivery’s strong infrastructure and technological capabilities position it well to capture this growth.
Conclusion: Navigating the Post-Acquisition Phase
Delhivery’s latest quarterly performance paints a picture of a company at a critical juncture. While one-time integration expenses have temporarily pushed the company into the red, underlying revenue growth, operational efficiency, and strategic positioning indicate a promising path forward.
As the e-commerce logistics sector continues to boom, all eyes will be on Delhivery to see whether it can turn this temporary setback into a launchpad for accelerated growth. Investors and industry watchers alike will be monitoring the next few quarters closely to see if Delhivery can fully capitalize on its expanded capabilities and reclaim consistent profitability.